Whitepaper V4.1
16. Treasury, Liquidity, Operations and Reserve Accounting
Approved
Last updated: October 16, 2026Version 1.0Maintainer: IONONSource: Whitepaper V4.1 canonical SHA-256 23b8e12be2fab3bcbaee6f5539964b2e299ae67be33e4d4d6962ccb57da0e01d
Whitepaper V4.1
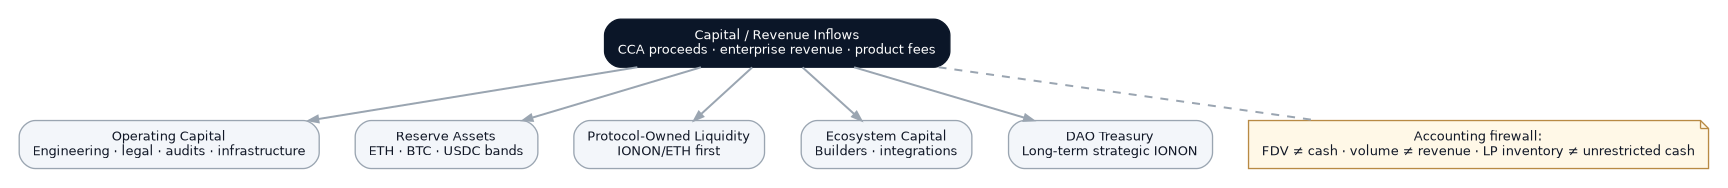
IONON uses separate balance sheets for separate economic purposes.
DAO Treasury is long-term strategic capital and IONON reserves under governance.
Liquidity is inventory and counter-asset committed to market depth.
Operating Capital pays engineering, audits, legal, infrastructure, staff and product execution.
Reserve Assets are risk-managed external assets such as ETH, BTC and USDC held under a published policy.
Ecosystem Capital funds grants and integrations.
Team Vesting contains contributor grants, not operating cash.
These categories must not be mixed in one unlabeled wallet.
A Capital Formation Circuit Breaker should also exist. The working policy target is that if cumulative primary-distribution proceeds reach a predefined threshold such as $10M, additional primary distribution pauses automatically for a comprehensive capital-need, dilution, adoption, liquidity and runway review. Raising more capital should not be an end in itself.
Every wallet and bank account should map to a ledger account and policy owner. At minimum the monthly close should reconcile: corporate cash, ETH/BTC/USDC reserves, DAO IONON, protocol-owned LP inventory, vesting contracts, distribution vaults, bridge escrow, card prefunding, payables/receivables and any custodial balances.
Financial reporting must separate:
A treasury policy should define target runway, minimum stable reserve, maximum single-asset concentration, permitted venues/custodians, signer quorum, counterparty limits, rebalancing bands and emergency liquidity. ETH exposure can be strategically useful at Genesis, but payroll and critical operating obligations should not depend on ETH remaining above a particular price.
IONON should borrow the strongest principle from exchange Proof-of-Reserves programs without pretending to be an exchange: do not ask stakeholders to trust what can be proven. Labeled addresses, signed wallet-control proofs, reconciled snapshots and independent accounting review can prove treasury existence and allocation. Where liabilities or restricted obligations exist, asset-only screenshots are insufficient; the disclosure must explain what the assets are committed to.