Whitepaper V4.1
Appendix C — CFO / CRO Economic Operating System
Approved
Last updated: October 16, 2026Version 1.0Maintainer: IONONSource: Whitepaper V4.1 canonical SHA-256 23b8e12be2fab3bcbaee6f5539964b2e299ae67be33e4d4d6962ccb57da0e01d
Whitepaper V4.1
IONON separates capital formation, treasury policy, market infrastructure, operating revenue and token-market value. The CFO function is responsible for solvency, runway, capital efficiency and evidence. The CRO function is responsible for repeatable external revenue, distribution and adoption. Neither function should use token price as a substitute for operating performance.
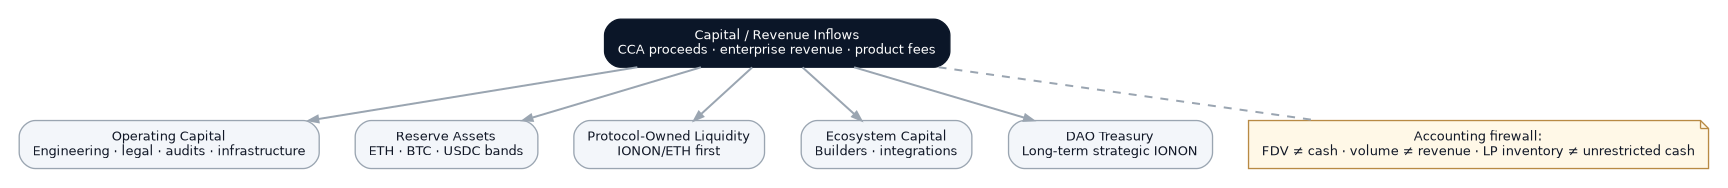
The minimum accounting architecture has six separately labeled domains:
| Domain | Primary assets | Purpose | Prohibited shortcut |
|---|---|---|---|
| DAO Treasury | IONON + governed external assets | Long-term protocol capital | Payroll from unlabeled treasury transfers |
| Liquidity | IONON + ETH/USDC/WBTC inventory | DEX/CEX market depth | Treating LP inventory as operating cash |
| Operations | Fiat/stablecoins/ETH as approved | Engineering, legal, security, payroll, infrastructure | Financing recurring burn by opaque token transfers |
| Reserve | ETH/BTC/USDC/other approved reserves | Runway protection and risk management | Market making without policy limits |
| Ecosystem | Budgeted grants/integrations | Builders, distribution and partnerships | Grants without milestones/evidence |
| Team Vesting | Allocated IONON grants | Long-term contributor alignment | Freely transferable founder inventory |
Every wallet must have an owner, purpose, allowed transaction classes, approval policy, accounting treatment and public label when disclosure is appropriate.
Treasury decisions should be ordered by survival and network utility:
No public communication should describe a discretionary treasury purchase as a guaranteed price floor.
The target revenue stack is intentionally diversified:
The board/DAO reporting package should never collapse all value into market capitalization. It should report at least:
| Dimension | Core measurements |
|---|---|
| Company | ARR/MRR, gross margin, cash runway, burn multiple, enterprise pipeline, NRR, CAC/payback where measurable |
| Network | active agents, active principals, successful Orders, policy-denial rate, settlement volume, protocol revenue, operator count |
| Token | circulating supply, locked/wrapped supply, top-holder concentration, liquidity depth, daily turnover, realized volatility |
| Treasury | NAV by asset, runway, liquidity commitments, concentration limits, realized/unrealized P&L |
| Security | open critical findings, incident count, mean time to detect/respond, bug bounty status, key-policy exceptions |
| Distribution | verified Genesis interest, active wallets, partner-sourced users, conversion to real product usage |
Primary token distribution is a financing mechanism, not a business model. The working architecture preserves a capital-formation circuit breaker: once cumulative primary proceeds reach a governance-defined threshold—currently modeled around $10 million for review purposes—additional primary distribution pauses pending a formal analysis of runway, dilution, adoption, liquidity, security spend and capital need.
The threshold is a policy concept until ratified. Its purpose is to prevent the organization from selling additional scarce supply merely because the market will absorb it.